Sole product designer · UX + UI + regulatory flows
Product
KuCoin identity verification (app & web)
Target users
Retail crypto users in Australia and the EU, new and existing
Scope
AU and EU KYC MVPs, ASIC suitability test, existing-user migration
Team
1 PM, 1 compliance officer, 5 engineers
Why it mattered
In 2024 Australia and the EU both introduced stricter crypto KYC rules. Without compliant onboarding, the exchange risked losing access to two of its biggest markets, and the requirements kept changing while compliance negotiated with the regulators.
One short flow had to become two regulated journeys
Australian and European users used to share one five-step KYC flow. New rules in both regions required stricter Level 2 checks before anyone could reach derivatives, and each regulator asked for different things.
Before the new rules · AU + EU5 steps to spot + derivatives
Select country
Personal info
Scan ID
Scan face
Submit
After the 2024 rules
🇦🇺 AustraliaUp to 11 steps
Level 1 · unlocks spot
Select Australia
Scan ID
Scan face
Address
Terms & conditions
Submit Level 1
Level 2 · unlocks derivatives
Choose user type
Retail
Advanced verification
Knowledge test (3 questions)
Suitability test (13 questions)
Submit Level 2
Wholesale
Proof of assets
Terms & conditions
Submit
🇪🇺 Europe14 steps
Level 1 · unlocks spot
Select EU country
Terms & conditions
Personal info
Scan ID
Scan face
Signature
Submit Level 1
Level 2 · unlocks derivatives
Start advanced verification
Risk disclaimer
Appropriateness test
Declaration
Proof of address
Proof of assets
Submit Level 2
Tests added by the new rules: fixed wording, no hints allowed
One five-step flow became two regulated journeys: Australia splits retail from wholesale, and the EU adds disclosures and declarations.
🇦🇺 Australia · AUSTRAC + ASIC
Two user types, one fixed test
Type sets access. Each user is classified as retail or wholesale, and that decides what they can use.
Wording can't change. Retail users must pass ASIC's suitability test before using derivatives, and its questions can't be reworded or coached.
🇪🇺 Europe · MiCA
More screening, warnings users must read
Screening and classification. PEP and sanctions screening, investor risk classification, and source of funds above set thresholds.
No buried warnings. Risk warnings before key actions belong in the flow, not in the legal small print.
The design question
How do you make a strict, pass/fail compliance flow feel fair, without coaching users toward the right answers?Requirements also kept shifting during the build, so the design had to absorb change without losing its structure.
03 · Solution
Two flows on one shared core
Both markets share the same identity core (photo ID, face scan, personal details), then branch into their own Level 2 rules. Each screen asks for one thing and says what it unlocks.
Australia · AUSTRAC + ASIC
One choice, two branches: after basic verification, retail users take the suitability test (branch 1) and wholesale users upload evidence (branch 2).
Europe · MiCA
Disclosure before access: after identity and documents come the appropriateness test, disclosures and declarations, plus proof of assets above a threshold.
04 · Key decision
Teach outside the quiz, never inside it
The quiz went through four rounds. The hardest call was how to help users pass a test that compliance said no one could coach. Both sides had a fair point.
Compliance needed
A genuine assessment
Locked wording. ASIC's questions can't be reworded, simplified or explained.
No hints. Anything that points to an answer turns the test into coaching.
Users needed
A fair chance to pass
Not to fail cold. Novice users met legal questions about derivatives with nothing to prepare them.
Failing is costly. Two misses mean a 24-hour wait; a third means 12 months.
My criterion
Anything that points to an answer stays out of the quiz. Anything that explains the topic can sit before it.Compliance could check every guide screen against that line, and users could prepare without being told what to pick.
✓What shipped: educate before the gate
Problem
Novice users met a hard pass/fail quiz cold, so they either guessed or gave up.
Decision
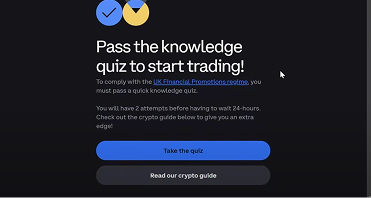
An optional crypto guide before the quiz. After a missed attempt, users see which topics to review and a way back to the guide.
Trade-off
No hints inside the quiz itself. The guide sits outside it, as education only.
The risk I accepted
The guide stays compliant only while it teaches concepts rather than mirroring questions, so every guide edit goes back through compliance. And because it's optional, some users will still skip it and take the test cold.
Two decisions that supported it
Benchmarking five exchanges showed two patterns in all of them: education before the test, which backed the guide, and one question per page.
01One question per page
Problem
A long scrolling quiz of fixed legal wording was quick to build but hard to read.
Decision
One question per screen, with progress by topic so users see the full scope up front.
Trade-off
More taps, in exchange for comprehension where it legally matters.
02Let users choose their path
Problem
In Australia, retail and wholesale users had different requirements and benefits, and there was no existing pattern to follow.
Decision
A user-type choice at the start of Level 2 that shows what each path asks for and unlocks. Then it branches: retail to the suitability test, wholesale to evidence upload.
Trade-off
One extra choice up front, so no one sees steps that don't apply to them.
How five exchanges handle itCoinbase · Binance · Kraken · OKX · Bitget
Coinbase
Guide before the quiz: educate, then assess.
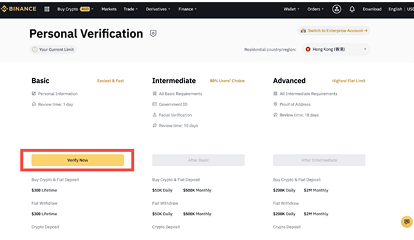
Binance
Levels side by side: each benefit is explicit.
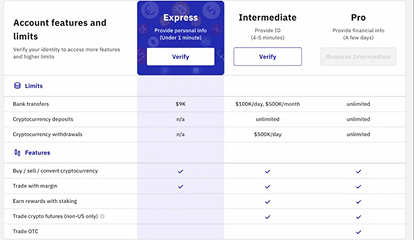
Kraken
One matrix: time to complete vs. limits unlocked.
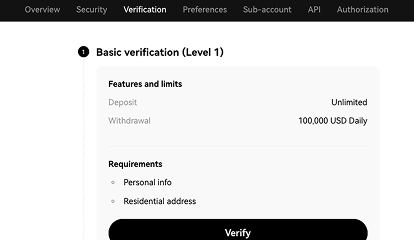
OKX
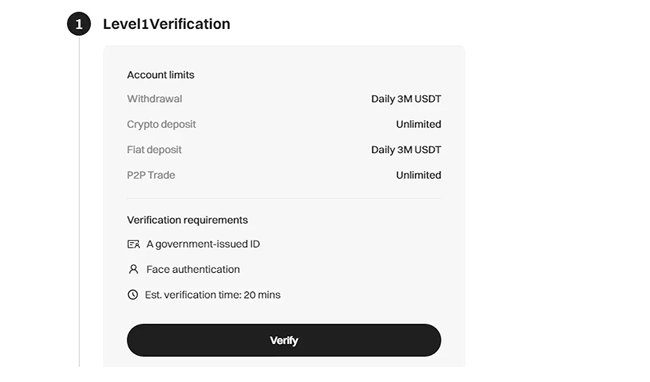
Requirements first: limits listed before one Verify button.
Bitget
Benefits up front: what each level earns.
05 · Changing rules
Three key-flow changes in three weeks of design
Design ran on and off, about three weeks in total: two drafts, three changes to the key flow as the rules moved, development support, and a one-day clean-up for the licence demo. I worked directly with compliance and legal, aligning on a wireframe before each change to the flow.
Month 1 to Month 3: design ran on and off across these months, and the identity flow changed as AU and EU requirements moved.
06 · Framework
One core, one branch per market
Once both markets shipped, I pushed to systematise these patterns into a modular KYC framework: one global identity core, plus a regional branch per jurisdiction. The team adopted it as the starting point for the next markets.
A new market becomes a new branch, not a new flow.
Each screen type (forms, questionnaires, declarations, document upload) is designed once and composed per jurisdiction, which kept the two markets consistent.
Page modules shared by AU and EU.
How the framework scalesCore · branches · new markets
Global core. Identity, document capture, liveness and result states, defined once and used in both markets.
Regional branches. The EU adds the knowledge guide, MiCA quiz and risk disclosures. Australia adds the retail/wholesale choice that gates the ASIC assessment.
Expansion model. A new market means defining its rules and composing a branch, not rebuilding the flow.
Component modules and verification statesLanding pages · info blocks · step states
Landing pages, required-information blocks and every verification step state.
User migration: re-verify without starting overMoving to the EU entity
Existing users moving to the EU entity had to re-verify under MiCA. Instead of starting over with a blank account, the flow reads where each user already is and asks only for what MiCA still requires.
State mapping
Only the missing steps
Each starting verification level maps to the minimum extra steps.
Communication
Why you're asked again
Explains the reason and what happens if you don't act, without alarming users.
Recovery
Partial completion is a state
A user halfway through can see where they are and pick it up later.
Migration from the main exchange to the EU entity.
07 · Result & reflection
Used in the MiCA application, built to extend
MiCA licence granted
The EU flow was demoed to the regulator as part of KuCoin's MiCA licence application.
AUSTRAC registration confirmed
The Australian entity is registered with AUSTRAC.
The crypto guide shipped
Compliance accepted it as education, not coaching, so it shipped as a product feature.
A template for new markets
The team adopted the modular framework as the starting point for the next markets.
On metrics: no usability testing ran before launch, and I don't have post-launch funnel data: these were compliance-gated MVPs, so the bar was clearing the regulator. Next, I'd measure first-attempt pass rate (with and without opening the guide) and Level 2 completion against the old five-step flow.
What I learned
01
Compliance is a design material
The best decisions, like the pre-quiz guide, came from designing with the compliance officer in the room, not around them.
02
Still open: test the guide with novice users
Whether the guide actually helps novices pass is still an assumption. Next, I'd run it with first-time derivatives users and compare pass rates after reading it.
Tap the image or press ← → to move through the walkthrough · Esc to close